Use case: Amazon KDP
Amazon KDP tax interview for non-U.S. authors: the W-8BEN walkthrough (also Associates and Merch)
Amazon's tax interview is Form W-8BEN behind a wizard. This guide maps every question to the form, shows the treaty rate for your country, and explains what KDP, Associates, and Merch withhold if you skip it.
If you publish on Kindle Direct Publishing from outside the United States, Amazon will not let you publish a book until you finish its tax interview. KDP’s help centre is blunt: “We must receive and validate your tax identity before you can update existing books or publish new books in the Kindle store.” The interview never says “W-8BEN” on its opening screen, but for a non-U.S. individual that is exactly what it produces. Amazon’s FAQ says the answers “will create the appropriate tax form on your behalf”. For a non-U.S. person that form is W-8BEN, or W-8BEN-E for a company.
Answer it well and Amazon withholds only your treaty rate on the U.S.-source part of your royalties. Skip the treaty section and Amazon withholds 30%. The same interview, and the same form, sits behind Amazon Associates and Merch on Demand, so one careful pass covers all three. This guide is educational information, not tax advice.
What Amazon withholds, and from which royalties
KDP withholds U.S. tax on the royalties it treats as U.S.-source income. Its help page draws the line precisely: “Royalty payments for eBook sales on Amazon.com and print book sales on Amazon.com, Amazon.co.jp, Amazon.com.au, and Amazon.ca are subject to 30% US tax withholding.” Ebook sales on the non-U.S. stores are outside that sentence and are not subject to U.S. withholding.
| Comparison | Interview not completed | W-8BEN, no treaty | W-8BEN with a treaty claim |
|---|---|---|---|
| Can you publish? | No. KDP blocks new titles and edits until the tax profile is validated. | Yes | Yes |
| Rate | Not applicable, nothing is paid | 30% (statutory rate) | 0% to 30%, depending on the treaty |
| Applied to | Not applicable | U.S.-source royalties only | U.S.-source royalties only |
| Example: $1,000 royalties, $600 U.S.-source | Not applicable | $180 withheld | $0 (UK, 0%) or $90 (India, 15%) |
| Year-end statement | None | Form 1042-S | Form 1042-S |
Three points sit behind those numbers.
- The 30% figure is the statutory rate, not an Amazon penalty. The IRS instructions state that foreign persons are subject to U.S. tax at a 30% rate on U.S.-source royalties. KDP calls it the default rate and says you may be eligible for a reduced rate under a treaty.
- A treaty claim needs a tax number. KDP says a reduction of the 30% rate “will not apply until you can provide a TIN”. Your home-country number counts, as the next section explains.
- Two other withholdings are not U.S. tax. KDP states that sales on Amazon.com.br carry 15% Brazilian withholding, and that sales on Amazon.in carry 10% Singaporean withholding for non-Singapore publishers. A W-8BEN does nothing about either.
Associates works the same way for commissions. Its help centre says the IRS requires Amazon to withhold up to 30% from non-U.S. associates earning referral commissions in the U.S., unless they provide “a completed W-8BEN with a valid claim of treaty benefits.”
Where the interview lives in KDP, Associates, and Merch
KDP’s path, from its “Complete Tax Profile” page:
- Sign in to KDP and open Your Account.
- Go to Tax Information.
- Select Complete Tax Profile. If you have already filed once, the button reads Update/Review Tax Profile.
KDP requires the profile before you publish, not just before you are paid. Associates puts the gate at payment instead: “The tax interview must be completed and validated with the Internal Revenue Service (IRS) before you can receive payment of commissions.” The Associates path is Account Settings, then View/Provide Tax Information, then Take Interview. To change an existing answer, the same page lists Change your Tax Information under Payment and Tax Information.
Merch on Demand uses the same Amazon interview, reached from the tax information area of your Merch account settings. Amazon publishes one “Tax Information Interview Guide” for all its programs. The questions and the forms it generates are the same wherever you open it. Amazon Tax Central, at taxcentral.amazon.com, is the shared hub for year-end statements. KDP tells publishers to sign in there with their KDP credentials and open Tax statements to download a 1042-S.
Before you open the tool
Have these ready. The interview is quick when you do not have to hunt for anything mid-way.
- Your legal name, exactly as your tax authority records it. KDP warns that a misspelled name, a missing middle name, or a wrong tax number “may cause a mismatch”. Pen names go on your book cover, not on this form.
- A permanent residence address in the treaty country. The IRS instructions rule out a post office box or an address used solely for mailing. A U.S. address on a W-8 invites questions about whether you are a U.S. person.
- Your foreign tax identification number. KDP states: “If you do not have a US TIN, you may enter the income tax identification number issued to you by the tax authority in your country of residence.” That is a UTR in the UK, a PAN in India, a Steuer-ID in Germany, and so on. You do not need an SSN, ITIN, or EIN.
- Your treaty rate and article. Use the selector further down. The interview picks the treaty from your country, but knowing the expected rate lets you catch a wrong answer before you sign.
- Consent to electronic signature. The interview asks for it at the end. Decline it and Amazon expects a mailed paper form, which KDP says “can take 5-6 weeks to receive and process”.
Prepare and review your answers in our tool
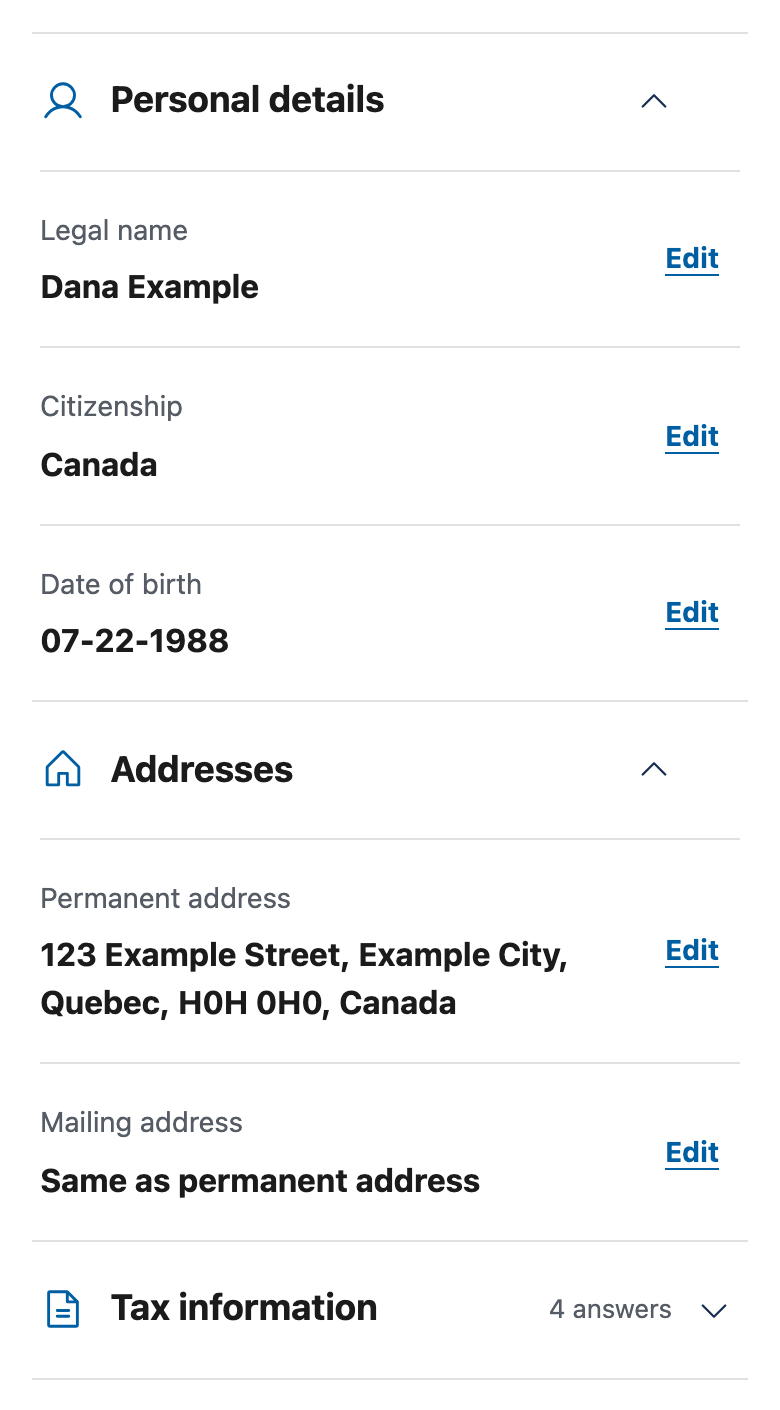
The answer-review panel in our W-8BEN interview, using the fictional Dana Example fixture. This is our preparation tool; a payer’s tax portal has its own screens and submission process.
Open full-size screenshotOpen full-size screenshot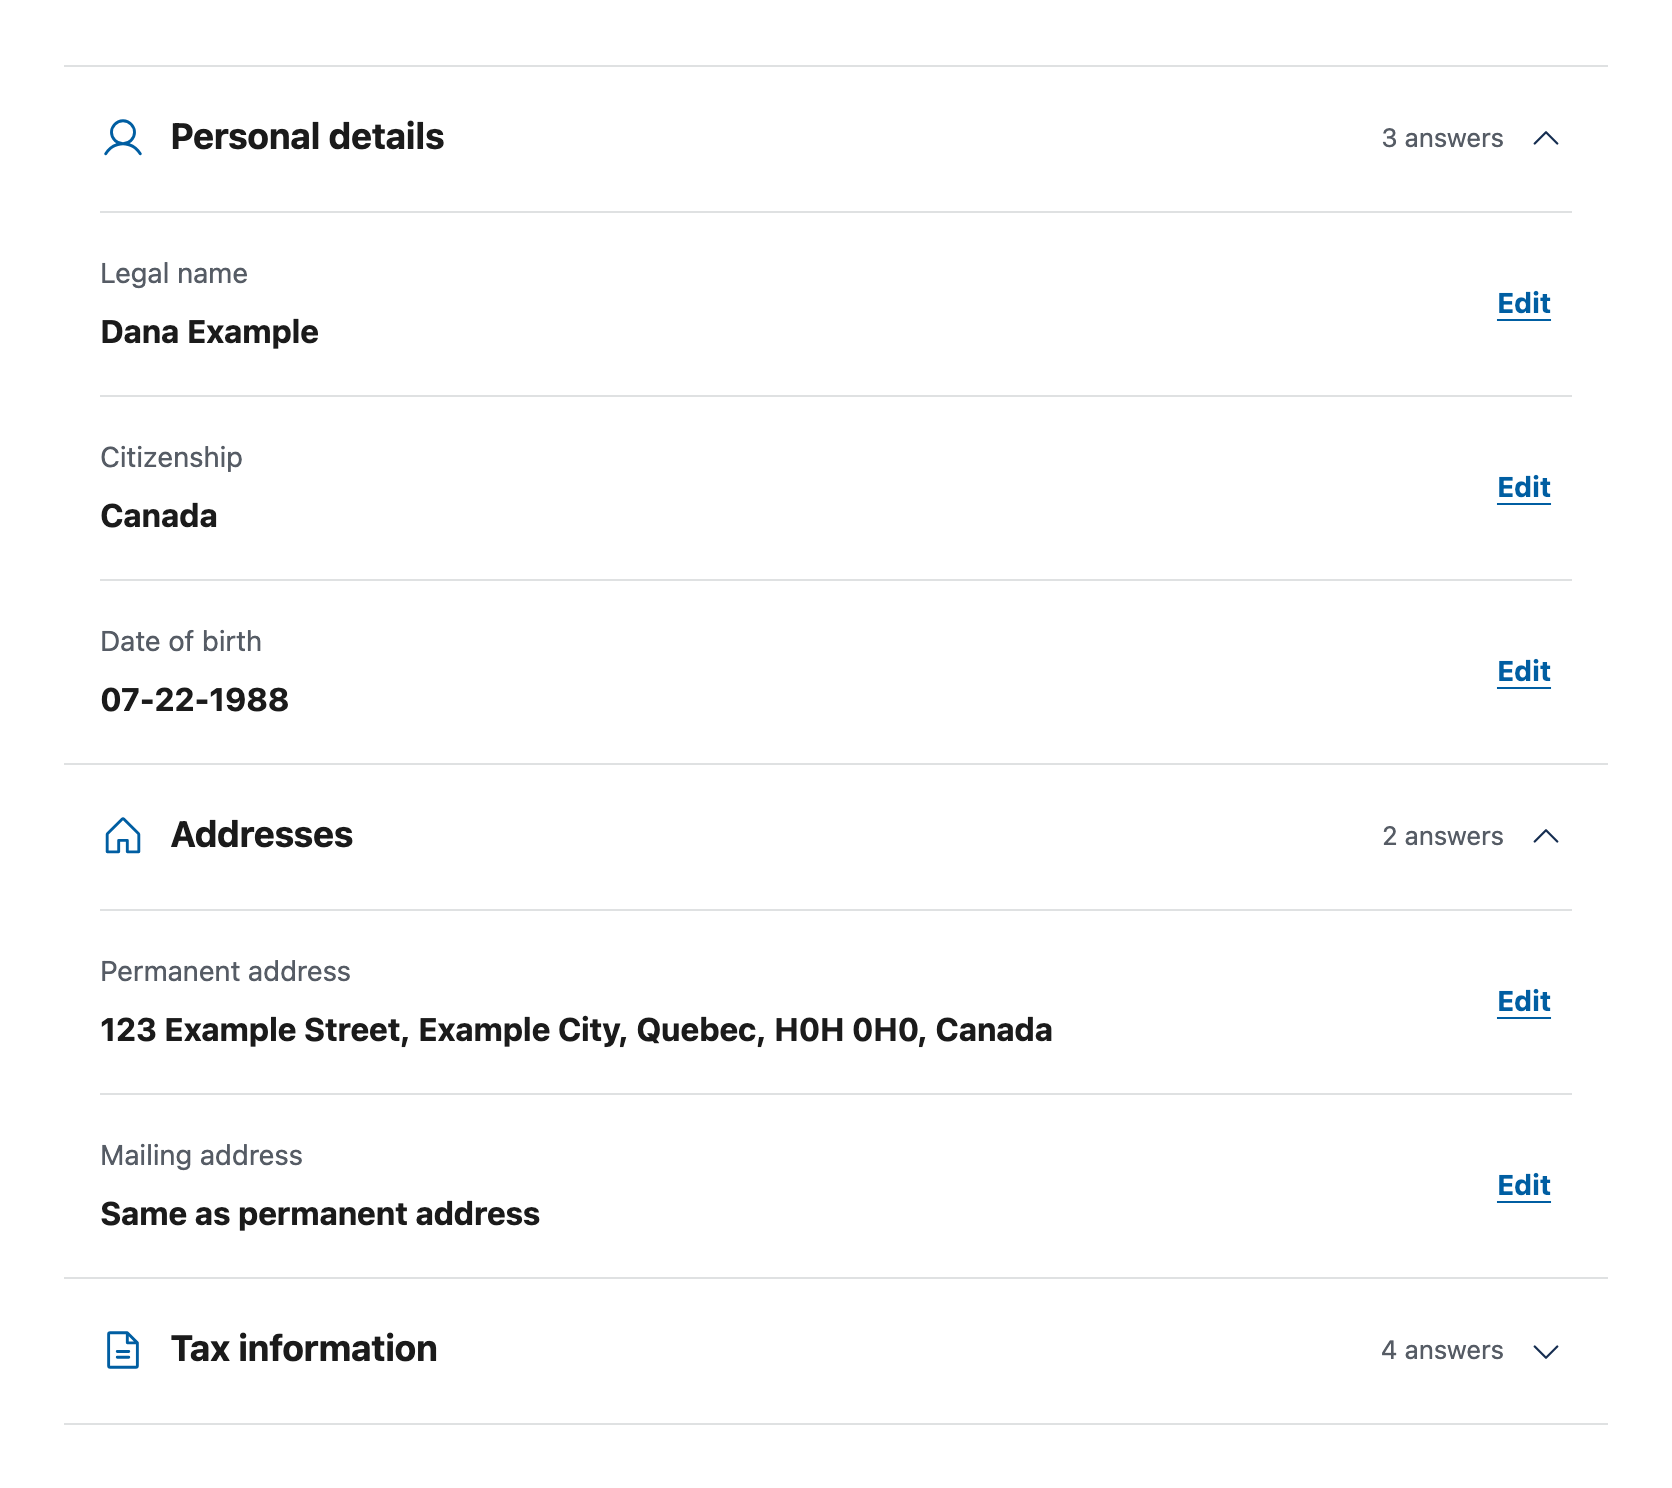
- Review the answers in each section
Check Personal details and Addresses, then expand Tax information to review the remaining answers.
Back to screenshot - Use Edit to correct an answer
Each Edit button returns to that question so you can correct it before continuing. Completing and reviewing the answers is free; signing and downloading come after payment.
Back to screenshot
Amazon’s questions, mapped to Form W-8BEN
Amazon’s interview guide lists the questions in this order: U.S. person status, tax classification, name, address, tax identification number, treaty benefits, and electronic signature. The table shows where each one lands on the official form so you can check the preview before you sign.
| Screen in Amazon’s tax interview | What it becomes | What to enter |
|---|---|---|
| For U.S. tax purposes, are you a U.S. person? | “Yes” switches to Form W-9 | Non-U.S. authors answer no. U.S. citizens and green-card holders living abroad are still U.S. persons and file W-9 instead. |
| Tax classification: Individual or Business | Chooses W-8BEN (individual) or W-8BEN-E (entity) | Pick individual if royalties are paid to you personally. Pick business only if a company is the payee. |
| Full name | W-8BEN Line 1 | Your legal name as it appears on your passport and in your tax authority’s records. Not a pen name or imprint. |
| Country of citizenship | W-8BEN Line 2 | Your citizenship, which may differ from the country whose treaty you claim. |
| Permanent address | W-8BEN Line 3 | A street address in the country where you are tax resident. No PO box, no “care of”, no U.S. address. |
| Mailing address (if different) | W-8BEN Line 4 | Optional. Leave blank when it matches your permanent address. |
| U.S. tax identification number | W-8BEN Line 5 | Optional. Most authors have none and leave it blank. |
| Foreign (non-U.S.) income tax identification number | W-8BEN Line 6a | Your home-country tax number. Amazon accepts it in place of a U.S. TIN for treaty claims. |
| Reference number | W-8BEN Line 7 | Optional. Leave blank. |
| Date of birth | W-8BEN Line 8 | Required for individuals on the current form. |
| Are you claiming treaty benefits? Country of residence for treaty purposes | W-8BEN Line 9 | Yes, if your country appears in the table below with a rate under 30%. Enter the country of tax residence. |
| Type of income and treaty article | W-8BEN Line 10 | Royalties. The interview selects the article and rate from your country. Compare it against the selector on this page. |
| Do you perform services in the United States? | Not on W-8BEN | Most authors answer no. Associates warns that saying yes can push withholding back to 30% and may call for a different form. |
| Document preview | The generated Form W-8BEN PDF | Check name, address, TIN, and the treaty rate before continuing. |
| Consent to electronic signature, then sign | W-8BEN Part III | Type your legal name. Sign as yourself. The capacity box on the generated form certifies you may sign; a free-text capacity field is only for someone signing on another person’s behalf. |
Two rows deserve a closer look.
Individual or business
KDP pays the person or entity named in your account’s payee details. If that payee is you, a sole trader trading under your own name, or a pen name with no legal existence, choose individual. If royalties are paid to a limited company, an LLC formed outside the United States, or a partnership, choose business. That path produces Form W-8BEN-E, covered later on this page.
The services question
Amazon’s Associates help gives a useful example. A UK associate posting links to a U.S. site is not treated as performing services in the United States. Writing a book at home and selling it on Amazon.com is the same idea. Book royalties are royalties, not payment for services. Answer no unless you physically work in the United States.
Treaty rate for your country
Choose your country of tax residence. The result shows the IRS treaty table rate for copyright royalties and the article you should see on Line 10 of the generated form. The film-and-TV rate is included for comparison.
Withholding rates on U.S.-source royalties by treaty country
Transcribed from IRS Tax Treaty Table 1, columns for film and television royalties (income code 11) and copyright royalties (income code 12).
Your selection stays in this browser tab and is not sent anywhere.
Show the full table for every treaty country
| Country | Copyright royalties | Film and TV royalties | Treaty article |
|---|---|---|---|
| Armenia | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Australia | 5% | 5% | 12(2) / P8 |
| Austria | 0% | 10% | 12(1), (2) |
| Azerbaijan | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Bangladesh | 10% | 10% | 12(2) |
| Barbados | 5% | 5% | 12(2) / 1PV; 2PII(6) No treaty benefit if the recipient is under a special low-tax regime (Table 1 footnote rr). |
| Belarus | 30% | 30% | Treaty partially suspended The IRS lists the U.S.–U.S.S.R. treaty as partially suspended for Belarus. Treat the rate as 30% unless a tax adviser confirms otherwise. |
| Belgium | 0% | 0% | 12(1) |
| Bulgaria | 5% | 5% | 12(2) / P5(7) |
| Canada | 0% | 10% | XII(2), (3) / 5P7(1) |
| Chile | 10% | 10% | 12(1)–(6) |
| China | 10% | 10% | 11(2) |
| Cyprus | 0% | 0% | 14(1) |
| Czech Republic | 0% | 0% | 12(2) |
| Denmark | 0% | 0% | 12(1) |
| Egypt | 15% | Not covered by the royalty article | 13(1) |
| Estonia | 10% | 10% | 12(2) |
| Finland | 0% | 0% | 12(1) |
| France | 0% | 0% | 12(1) / 2PIII |
| Georgia | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Germany | 0% | 0% | 12(1) |
| Greece | 0% | 30% | VII |
| Hungary | 30% | 30% | Treaty terminated The IRS lists the U.S.–Hungary treaty as terminated. The statutory 30% rate applies. |
| Iceland | 0% | 5% | 12(1), (2) |
| India | 15% | 15% | 12(2)–(4) |
| Indonesia | 10% | 10% | 13(2) / P34 |
| Ireland | 0% | 0% | 12(1) |
| Israel | 10% | 10% | 14(1) |
| Italy | 0% | 8% | 12(2) Italy taxes software royalties at the industrial-equipment rate rather than the copyright rate (Table 1 footnote tt). |
| Jamaica | 10% | 10% | 12(2) |
| Japan | 0% | 0% | 12(1) |
| Kazakhstan | 10% | 10% | 12(2) |
| Kyrgyzstan | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Latvia | 10% | 10% | 12(2) |
| Lithuania | 10% | 10% | 12(2) |
| Luxembourg | 0% | 0% | 13(1) |
| Malta | 10% | 10% | 12(2) |
| Mexico | 10% | 10% | 12(2) |
| Moldova | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Morocco | 10% | 10% | 12(2) |
| Netherlands | 0% | 0% | 13(1) |
| New Zealand | 5% | 5% | 12(2) / PVIII |
| Norway | 0% | Not covered by the royalty article | 10(1) |
| Pakistan | 0% | Not covered by the royalty article | VIII(1) Payments for TV broadcasting rights fall under the royalty article, but rental income from motion picture films does not (Table 1 footnote u). |
| Philippines | 15% | 15% | 13(2) The Philippine domestic rate differs from the U.S. treaty rate (Table 1 footnote vv). |
| Poland | 10% | 10% | 13(2) |
| Portugal | 10% | 10% | 13(2) |
| Romania | 10% | 10% | 12(2) |
| Russia | 30% | 30% | Treaty partially suspended The IRS lists the U.S.–Russia treaty as partially suspended, and the suspension covers the royalties article. Treat the rate as 30%. |
| Slovak Republic | 0% | 0% | 12(2) |
| Slovenia | 5% | 5% | 12(1) |
| South Africa | 0% | 0% | 12(1) |
| South Korea | 10% | 10% | 14(1) |
| Spain | 0% | 0% | 12(1) / PVI |
| Sri Lanka | 10% | 10% | 12(2) |
| Sweden | 0% | 0% | 12(1) |
| Switzerland | 0% | Not covered by the royalty article | 12(1) |
| Tajikistan | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Thailand | 5% | 5% | 12(2) |
| Trinidad and Tobago | 0% | Not covered by the royalty article | 14(1) 15% for copyrights of scientific work (Table 1 footnote cc). |
| Tunisia | 15% | 15% | 12(2)–(3) |
| Turkey | 10% | 10% | 12(2) |
| Turkmenistan | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Ukraine | 10% | 10% | 12(2) |
| United Kingdom | 0% | 0% | 12(1) |
| Uzbekistan | 0% | 0% | III(1)(a) (U.S.–U.S.S.R. treaty) |
| Venezuela | 10% | 10% | 12(2) |
| Any other country | 30% | 30% | No treaty. Common examples: Argentina, Brazil, Colombia, Ghana, Hong Kong, Kenya, Malaysia, Nigeria, Peru, Saudi Arabia, Singapore, Taiwan, United Arab Emirates, Vietnam. |
Read before relying on a rate: figures are transcribed from IRS Tax Treaty Table 1 (Rev. May 2023), columns for income codes 11 and 12. The table itself warns that it is not a complete statement of eligibility. Limitation-on-benefits rules, residence tests, and the payer's own review can change the outcome.
Why does the copyright column apply to books? A KDP royalty pays you for the right to reproduce and sell a work you hold the copyright in. Treaty royalty articles cover payments for the use of a copyright in a literary, artistic, or scientific work. A novel or a textbook is a literary work in the plainest sense. The IRS treaty table places those payments under income code 12, copyright royalties. That is the column the selector leads with, and the rate Amazon should apply once your interview is validated.
The zero-rate group includes the United Kingdom, Ireland, Germany, France, Spain, the Netherlands, Japan, South Africa, and Canada. India and the Philippines are at 15%, Mexico, Poland, Portugal, South Korea, and Turkey at 10%, and Australia, New Zealand, and Thailand at 5%. Authors in Brazil, Nigeria, Singapore, the UAE, Vietnam, and other countries with no treaty still file W-8BEN, without a treaty claim, and are withheld at the statutory 30%.
Why the interview is flagged or re-requested
KDP validates your answers and shows a status on the Tax Information page. Complete means “your KDP account is in good standing” and shows the withholding rate applied. Under review means Amazon “will let you know if more information is necessary”. Incomplete blocks publishing. These are the causes KDP and Associates list, or that follow from the rules above.
- Name mismatch. KDP says a misspelled name, a missing middle name, or a wrong TIN “may cause a mismatch”. Use the name your tax authority holds, not a shortened or anglicised version.
- Missing tax number on a treaty claim. Without a foreign or U.S. TIN, KDP applies 30% even when your country has a treaty.
- Treaty not claimed. Associates’ first explanation for 30% withholding after a completed interview is that “an appropriate treaty has not been claimed”. Retake the interview and answer yes to treaty benefits.
- Services inside the United States. Associates’ second explanation is that you said you provide services both inside and outside the U.S.
- U.S. address or PO box. A W-8 certifies foreign status, and a U.S. permanent address contradicts it. A PO box fails the IRS Line 3 rule.
- Recently issued TIN. KDP notes that a newly issued U.S. TIN “can take up to 60 days” to reach the IRS database.
- Mismatch left unfixed. KDP gives you 30 days to update the profile after a mismatch, or it suspends your ability to publish.
The fix in every case is the same path: Your Account, Tax Information, Update/Review Tax Profile, and retake the interview.
How long the form lasts
Life of a W-8BEN submitted through Amazon's tax interview
Amazon follows the IRS rule. KDP puts it this way: the W-8 expires on the last day of the third succeeding calendar year from the date signed.
You sign the form in the KDP tax interview
KDP validates the profile. Once the status shows Complete, the treaty rate applies to U.S.-source royalties from the next payment cycle.
Your address, country, or name changes
The IRS instructions require you to notify the payer within 30 days of a change in circumstances. Amazon's interview guide says to do this by retaking the interview.
March 15 each year
KDP issues Form 1042-S on or before March 15 for the previous year. Download it in KDP under Tax Information or on Amazon Tax Central under Tax statements.
December 31, 2029
The form expires at the end of the third full calendar year after 2026. KDP warns that a reduced rate will default back to 30% if you allow the W-8 to expire, so update the profile before then.
Important: The example dates assume a signature in 2026 and no change in circumstances. A move to another country or a change of legal name ends the form's validity early.
Worked examples
All three authors are fictional. Each earns $1,000 in KDP royalties in a month. Of that, $600 is U.S.-source: ebook sales on Amazon.com plus print sales on the U.S., Japanese, Australian, and Canadian stores. The other $400 comes from ebook sales on Amazon.co.uk, Amazon.de, and Amazon.in and is not U.S.-source.
Tessa Marlowe, a fantasy author in the United Kingdom. She completes the interview with her UTR on Line 6a and claims the UK treaty. The copyright royalty rate is 0%, so Amazon withholds nothing on the $600. Had she skipped the treaty section, Amazon would have withheld 30% of $600, which is $180.
Arjun Vellore, a non-fiction author in India. He enters his PAN and claims the India treaty at 15%. Amazon withholds 15% of $600, which is $90. The $400 from non-U.S. stores is untouched by U.S. withholding, though the Amazon.in portion carries the separate 10% Singaporean withholding KDP describes.
Chidi Okonkwo, a thriller author in Nigeria. Nigeria has no income tax treaty with the United States. He files W-8BEN without a treaty claim, Amazon withholds 30% of $600, which is $180, and reports it on Form 1042-S. The form still matters: without a validated tax profile he could not publish at all.
Authors who publish through a company
Is your KDP payee a limited company, an imprint with its own legal identity, or another entity separate from you? Then choose Business in the interview. Amazon generates Form W-8BEN-E, which asks about the entity’s classification and its limitation-on-benefits status under the treaty. The questions are longer and the mistakes are different. Our W-8BEN-E interview walks through that form line by line. If you are unsure which form fits, the which W-8 form guide settles it in a few questions.
Frequently asked questions
Do I need to complete the KDP tax interview before I can publish?
Yes. KDP states that it must receive and validate your tax identity before you can update existing books or publish new books in the Kindle store. Associates places the gate at payment instead, but the interview is the same.
Is the Amazon tax interview the same thing as Form W-8BEN?
For a non-U.S. individual, yes. Amazon's FAQ says the answers you give create the appropriate tax form on your behalf, and for non-U.S. individuals that form is W-8BEN. Non-U.S. companies get W-8BEN-E, and U.S. persons get W-9.
Do I need a U.S. tax number (ITIN or EIN) to claim a treaty rate on KDP?
No. KDP says that if you do not have a U.S. TIN, you may enter the income tax identification number issued by the tax authority in your country of residence. A UK UTR, an Indian PAN, or a German Steuer-ID is enough. A reduced rate does not apply until some TIN is on file.
Which of my KDP royalties are subject to U.S. withholding?
KDP lists ebook sales on Amazon.com and print book sales on Amazon.com, Amazon.co.jp, Amazon.com.au, and Amazon.ca. Ebook sales on the other stores are not subject to U.S. withholding. Sales on Amazon.com.br carry a separate 15% Brazilian withholding, and Amazon.in carries 10% Singaporean withholding, neither of which a W-8BEN changes.
My country has no tax treaty with the U.S. Should I still complete the interview?
Yes. KDP will not let you publish without a validated tax profile, and Associates will not pay commissions. Without a treaty, Amazon withholds the statutory 30% on U.S.-source royalties only. Royalties from non-U.S. stores are not withheld.
Where do I download my 1042-S from Amazon?
KDP issues Form 1042-S on or before March 15 each year. Download it in KDP under Your Account, Tax Information, Update/Review Tax Profile, in the Tax statements section, or sign in to Amazon Tax Central with your KDP credentials and open Tax statements. KDP issues it once global royalties across all Amazon businesses exceed $0.49.
Do Amazon Associates and Merch on Demand use the same tax interview as KDP?
Yes. Amazon publishes one Tax Information Interview Guide covering all its programs, and each program's account settings link to it. In Associates the path is Account Settings, View/Provide Tax Information, Take Interview. Year-end statements for every program are stored on Amazon Tax Central.
When does the W-8BEN I signed in the KDP tax interview expire?
KDP says the W-8 expires on the last day of the third succeeding calendar year from the date signed. A form signed in 2026 lasts until December 31, 2029. If a reduced treaty rate is in use and the form lapses, KDP warns withholding defaults back to 30%. The IRS also requires a new form within 30 days of a change in circumstances.